
Resources

ZestyAI and Mutual Capital Group Bring AI-Powered Property Intelligence to Underwriting Operations
ZestyAI today announced that Mutual Capital Group companies Tuscarora Wayne Insurance Company, Keystone National Insurance Company, and Lebanon Valley Insurance Company have selected ZestyAI's property analytics platform to bring real-time, property-level intelligence to their underwriting, pricing, and inspection decisions.
Mutual Capital Group is adopting two ZestyAI solutions across its personal and commercial lines underwriting operations. Z-PROPERTY™ evaluates roof complexity, materials, condition, and surrounding risk factors that directly influence loss potential and underwriting outcomes.
Roof Age delivers verified roof age by cross-validating building permit records with more than 20 years of aerial imagery, identifying roof replacement events that traditional records often miss and assigning a confidence score to every property.
"Getting accurate, property-level data on roof quality, roof age, hail exposure, and wind risk without relying solely on physical inspections is a significant operational advantage," said Bruce White, Senior Commercial Lines Underwriting Officer and Assistant Vice President at Mutual Capital Group. "ZestyAI gives our underwriters the verified intelligence they need to evaluate every risk with greater consistency and confidence. It also allows us to direct physical inspection resources more strategically, focusing on the policies that need them most."
"Mutual Capital Group recognized the value of adopting a comprehensive approach to property analytics," said Attila Toth, Founder and CEO of ZestyAI. "We're proud to support their underwriting teams with trusted insights that help sharpen risk selection, align pricing with exposure, and strengthen overall portfolio performance."

ZestyAI expands into the London market with MAP Underwriting partnership
Lloyd's of London managing agency adopts ZestyAI’s Z-FIRE™ to strengthen wildfire risk analysis across its property reinsurance portfolio
ZestyAI today announced MAP Underwriting (Managing Agency Partners), the Lloyd’s of London managing agency, as its first London-market customer. MAP has selected Z-FIRE™, ZestyAI’s wildfire risk model, to enhance how California wildfire exposure is evaluated and managed within its property (re)insurance portfolio.
The partnership marks ZestyAI’s first international expansion and highlights growing global concern from insurers about the impact of wildfires.
Operating Syndicate 2791 at Lloyd’s, MAP is widely respected for its underwriting discipline and technical approach to risk. The firm places exposure analysis at the center of its underwriting strategy, building its own view of risk by synthesizing the most relevant inputs while maintaining a deliberate balance of exposure across its portfolio.
In California, the structural and environmental conditions that drive loss can shift materially across short distances and change faster than broad-scale models can keep up with. That variability places a premium on the quality and resolution of the underlying data. Traditional models often smooth over these localized differences—introducing uncertainty into how exposure is differentiated and priced.
Z-FIRE addresses this gap by providing a more refined view of wildfire risk, predicting which properties are most likely to experience a wildfire and which are most likely to survive. Using computer vision and machine learning, the model captures how structural and environmental characteristics — defensible space, vegetation density, building materials, and topography — interact at the property level to drive loss outcomes, and is trained on the industry’s largest wildfire loss dataset.
Integrated into MAP’s underwriting framework, this intelligence strengthens its exposure analysis—helping the team more precisely distinguish wildfire risk across California and maintain a more consistent, data-driven understanding of portfolio exposure.
"At MAP, we build our own view of risk and rely on high-quality data that strengthens that perspective," said Nick Williams, Deputy Active Underwriter at MAP.
"Z-FIRE enhances MAP’s view of California wildfire risk with a higher-resolution view that integrates cleanly into our framework and supports more confident decisions across our portfolio."
"The London market is paying closer attention to wildfire than ever before, and the bar for hazard intelligence underneath that work has risen with it," said Attila Toth, Founder and CEO of ZestyAI. "MAP is one of the most respected property (re)insurance teams at Lloyd's, and partnering with them on California wildfire is a meaningful first step in bringing Z-FIRE to the broader London Market.
"This partnership highlights the growing international demand for greater risk intelligence solutions and marks an exciting new chapter for ZestyAI."

ACV roof endorsements jump 6x in a decade as carriers quietly rewrite homeowners insurance, ZestyAI analysis finds
Analysis of 2,000+ regulatory filings across more than 60 carriers reveals carriers are increasingly competing not on price, but on how policies present at claim time
The analysis is part of ZestyAI’s broader research into how coverage architecture is reshaping competition across P&C insurance. Download the full report, The New Competitive Battleground in P&C Insurance →
- Among the top 10 US homeowners carriers, ACV roof settlement schedules grew from 10% adoption in 2015 to 60% in 2025; percentage deductibles increased from 60% to 90% of policies over the same period
- Cosmetic damage and anti-matching provisions among the top 10 carriers accelerated from 20% adoption in 2015 to 90% in 2025
- Across all ~60 carriers reviewed in catastrophe-exposed states, 93% now use percentage deductibles, 75% use ACV roof settlement schedules, and 49% include cosmetic damage exclusions
- A single roof claim today routinely faces four or more stacked coverage restrictions from one loss event
New analysis by ZestyAI of more than 2,000 homeowners insurance regulatory filings reveals a decade-long, industry-wide rewrite of the homeowners contract - one that has left the modern homeowners policy structurally different from the one sold even a few years ago.
While rising catastrophe losses, rate pressure, and tighter underwriting continue to dominate industry discussion, the analysis identified a more consequential shift: carriers are increasingly competing not on headline price, but on how policies present at claim time.
Among the top 10 US carriers, adoption of Actual Cash Value (ACV) roof settlement schedules has jumped six-fold, from 10% of policies in 2015 to 60% in 2025, while percentage-based deductibles spread from 60% to 90% of policies over the same period. Cosmetic damage and anti-matching provisions, once rare, have accelerated even faster: from 20% adoption in 2015 to 90% in 2025.
Using its regulatory intelligence platform ZORRO Discover™, ZestyAI analyzed more than 2,000 homeowners insurance filings across approximately 60 carriers operating in catastrophe-exposed states including Texas, Oklahoma, Colorado, Ohio, and North Carolina. The data shows that coverage restrictions, once isolated endorsements or niche products, have become foundational elements of the modern homeowners insurance contract.
Across all carriers reviewed, the analysis found that:
- 93% use percentage-based deductibles
- 78% apply age-based coverage triggers
- 75% use Actual Cash Value (ACV) roof settlement schedules
- 49% include cosmetic damage exclusions
- 30% require mandatory inspections as a condition of coverage
- 17% include anti-matching language
The research shows that carriers facing similar catastrophe pressures are not converging on a single product design. Instead, they are assembling similar coverage controls in different combinations depending on geographic concentration, operating model, and risk appetite.
Texas showed 100% adoption of percentage deductibles among reviewed carriers, while Oklahoma reached approximately 95%. ACV roof settlement schedules were most prevalent in Oklahoma (85%) and Texas (82%), while cosmetic damage exclusions appeared in 57% of reviewed Texas filings and 50% in Colorado.
The analysis also found that coverage restrictions are increasingly layered together rather than introduced individually. In many filings, a single roof claim is simultaneously subject to a percentage deductible, an ACV settlement schedule, an age-based payout trigger, and a cosmetic damage exclusion - creating up to four constraints on recovery from one loss event.
Despite the spread of these restrictions, the analysis found that policyholder dissatisfaction has not yet materially increased. Across the filings examined, coverage restrictions showed a negative correlation with complaint volume - potentially reflecting the fact that these controls can help moderate premium increases at the time of bind. As a result, many policyholders may focus more on their immediate rate than changes to policy language, with the financial impact of coverage restrictions often becoming visible only when a claim occurs.
Stephanie Kuczynski, Director of Risk Analytics at ZestyAI, said:
“Two policies can look nearly identical at bind and behave very differently at claim time. The difference is that one may achieve a lower premium by layering restrictions that shift more risk back to the policyholder. Consumers naturally focus on the price they pay today, while the cumulative impact of a percentage deductible, an ACV roof settlement schedule, an age-based trigger, and a cosmetic exclusion often doesn't become clear until a loss occurs. That's why a decade-long trend like ACV adoption jumping six-fold matters: the economics of a roof claim under those policies can look fundamentally different.”
Roof Coverage Restrictions in Homeowners Insurance: 2015–2025 Adoption Trends From Regulatory Filings
Among the top 10 U.S. homeowners carriers, adoption of Actual Cash Value (ACV) roof settlement schedules has jumped sixfold in a decade, from 10% of policies in 2015 to 60% in 2025. That's the headline finding from a ZestyAI analysis of more than 2,000 homeowners insurance regulatory filings across roughly 60 carriers, cited in a P&C Specialist article published July 1, 2026, by Jennifer Ortakales Dawkins, with commentary from ZestyAI's Director of Risk Analytics, Stephanie Kuczynski, on what a decade of coverage changes means for carriers and policyholders.
For the broader research on how coverage design is reshaping P&C competition, download The New Competitive Battleground in P&C Insurance →
How are carriers using ACV roof settlement schedules to manage roof exposure?
Carriers use Actual Cash Value (ACV) roof settlement schedules to cap claim severity on older roofs: the schedule pays the replacement cost of a roof adjusted for age and depreciation, rather than the full cost of replacing it. ACV is one of several coverage controls carriers use to limit exposure on aging roofs, alongside percentage-based deductibles, cosmetic damage exclusions, age-based payout triggers, and anti-matching provisions.
How fast is ACV roof settlement adoption growing among homeowners carriers ?
Sixfold in a decade among the top 10 U.S. homeowners carriers, from 10% of policies in 2015 to 60% in 2025. Looking at all ~60 carriers ZestyAI reviewed in catastrophe-exposed states, 75% now use ACV roof settlement schedules.
What other roof coverage restrictions are carriers filing?
ACV schedules are only one of several controls carriers are adding. Percentage-based deductibles spread from 60% to 90% of top-10 carrier policies over the same 2015-2025 period. Cosmetic damage and anti-matching provisions — once rare, limiting payouts for damage that's visible but doesn't affect a roof's function — accelerated even faster, from 20% adoption in 2015 to 90% in 2025.
Across all ~60 carriers ZestyAI reviewed in catastrophe-exposed states, the adoption rates were: 93% use percentage-based deductibles, 78% apply age-based coverage triggers, 75% use ACV roof settlement schedules, 49% include cosmetic damage exclusions, 30% require mandatory inspections as a condition of coverage, and 17% include anti-matching language.
How are carriers stacking multiple roof coverage restrictions?
ZestyAI's analysis found that a single roof claim today routinely faces four or more stacked coverage restrictions from one loss event: a percentage deductible, an ACV settlement schedule, an age-based payout trigger, and a cosmetic damage exclusion can all apply simultaneously. Kuczynski described one common pairing: "Attaching a higher flat deductible to your policy specifically targeting wind and hail losses puts a lot more skin in the game for the insured and does help to reduce the cost when claim time does come."
Which states have the highest adoption of roof coverage restrictions?
Texas and Oklahoma lead. ZestyAI found Texas at 100% adoption of percentage deductibles among reviewed carriers, with Oklahoma at approximately 95%. ACV roof settlement schedules were most prevalent in Oklahoma (85%) and Texas (82%), while cosmetic damage exclusions appeared in 57% of Texas filings and 50% of Colorado filings. Carriers facing similar catastrophe pressure aren't converging on one product design; they're assembling the same controls in different combinations depending on geographic concentration, operating model, and risk appetite.
Do roof coverage restrictions increase policyholder complaints?
Not so far. ZestyAI cross-referenced coverage restrictions against state insurance department complaint volumes and found a negative correlation; filings with more restrictions were associated with fewer complaints, not more. "There are less complaints coming in immediately, and theoretically that is due to premium breaks," Kuczynski said. "Everybody likes to have more cash, but we're not seeing any pushback from insureds for this loss of coverage."
Why are carriers layering coverage restrictions instead of relying on rate alone?
Coverage design can target roof-specific severity in ways base rate changes cannot. Controls like percentage wind/hail deductibles and ACV schedules shift a defined share of each loss back to the insured, reducing claim costs while funding the premium relief that appears to be keeping complaint volumes down. For carriers facing rate pressure in catastrophe-exposed states, coverage architecture has become a second lever alongside rate.
What does coverage architecture mean for carrier competitive strategy?
Coverage architecture, how coverage restrictions are layered within a policy, now differentiates carriers as much as rate, because two policies can look nearly identical at bind and behave very differently at claim time, according to Kuczynski. "The difference is that one may achieve a lower premium by layering restrictions that shift more risk back to the policyholder. Consumers naturally focus on the price they pay today, while the cumulative impact of a percentage deductible, an ACV roof settlement schedule, an age-based trigger, and a cosmetic exclusion often doesn't become clear until a loss occurs. That's why a decade-long trend like ACV adoption jumping six-fold matters: the economics of a roof claim under those policies can look fundamentally different."
The broader takeaway: as coverage design increasingly shapes what a roof claim actually pays out, clearer visibility into how these terms are layered — for carriers designing products, regulators reviewing filings, and policyholders comparing coverage — is becoming as important as the rate itself.
How can carriers benchmark their roof coverage against competitors?
Approved regulatory filings show which controls competitors have filed, in which states, and in what combinations. ZestyAI’s analysis drew on more than 2,000 homeowners filings across roughly 60 carriers to quantify adoption of ACV schedules, percentage deductibles, cosmetic exclusions, and age-based triggers. ZORRO Discover gives carriers this filing intelligence on demand: competitor coverage language, adoption rates, and state-by-state comparisons, so product teams can see where their own coverage architecture sits relative to the market.
Read the full article Shrinking Roof Lifespans Create a Pricing Problem for Home Insurers → P&C Specialist, July 1, 2026, by Jennifer Ortakales Dawkins. Includes ZestyAI's regulatory filing analysis and commentary from Stephanie Kuczynski, ZestyAI's director of risk analytics.
DUAL North America Expands Partnership with ZestyAI to Power Wildfire Underwriting in California
Z-FIRE™ to support new California program with property-level wildfire risk intelligence.
ZestyAI today announced that DUAL North America(“DUAL”) is expanding its partnership with ZestyAI to power wildfire underwriting for a new California homeowners program. As part of this expansion, DUAL will use Z-FIRE™ to assess wildfire exposure at the property level and support disciplined growth in catastrophe-exposed regions.
California continues to present significant wildfire volatility, requiring insurers to move beyond broad geographic indicators toward more granular, property-specific insights. Z-FIRE uses machine learning to evaluate each property’s unique characteristics—including defensible space, vegetation proximity, topography, building materials, and surrounding fire behavior patterns—to predict wildfire vulnerability at the individual structure level.
This property-level insight helps insurers identify structures most likely to suffer catastrophic loss, and those far more likely to survive a wildfire event.
“Launching a California program requires a disciplined, data-driven approach to wildfire risk,” said Luke Wolmer, Chief Actuary at DUAL.
“Z-FIRE delivers the property-level insight we need to confidently assess exposure, differentiate risk within the same territory, and offer coverage with greater clarity and consistency. That level of precision is essential as we grow our portfolio with greater confidence.”
This expansion builds on DUAL’s late-2025 adoption of Z-STORM™ to strengthen hail and wind underwriting across its U.S. portfolio, marking a rapid expansion of its use of the ZestyAI platform.
“After strengthening severe storm underwriting with Z-STORM, DUAL is now extending that strategy to wildfire with Z-FIRE.” said Attila Toth, Founder and CEO of ZestyAI.
“This expansion shows how insurers can grow responsibly in challenging markets when decisions are grounded in verified, property-level intelligence.”
Z-FIRE is approved across Western wildfire markets and was the first AI-based wildfire model approved as part of a carrier rate filing in California. ZestyAI’s broader portfolio of risk models has secured more than 200 regulatory approvals nationwide.
Mitigation-Aware Scoring: When a Property Changes, the Score Can Too
Property risk changes over time, but property data doesn't always keep up. A roof is replaced. Defensible space is cleared. Vegetation is removed. These improvements can materially change risk, yet the data behind a score often lags behind the property itself. That can mean overpricing lower-risk homes and frustrating policyholders who invested in mitigation. Mitigation-Aware Scoring gives carriers a governed, auditable way to update verified property attributes within the ZestyAI platform and recalculate risk when those changes affect the score.
What Mitigation-Aware Scoring Does
Mitigation-Aware Scoring allows authorized users to update property attributes within the ZestyAI platform when they have more accurate or more current information.
Some property attributes are used as inputs to ZestyAI risk models and may change the property's risk score when updated. Other attributes are informational only and update the property record without affecting the risk score.
Once submitted, the updated value is stored for that carrier and made available to the underwriting, pricing, and operations teams, so they can make decisions from the same property view.
It supports two review paths:
- Carrier-initiated review: When an underwriter, risk team, or operations team determines a property attribute should be adjusted, they can update it in the platform with an auditable record.
- Policyholder, agent, or inspection updates: When new information comes from a homeowner, agent, field inspection, or third-party source, authorized users can apply that information directly on the platform after the carrier's review process.
How Mitigation-Aware Scoring Works
The workflow happens in the ZestyAI platform:
- Search for the property by address
- Review property features and current model inputs
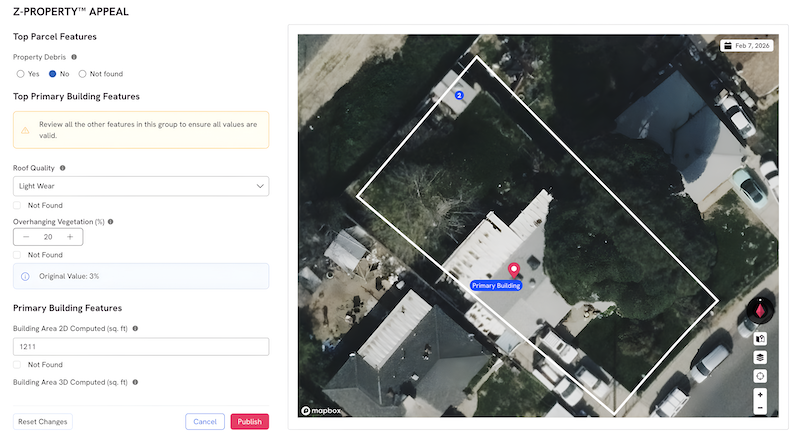
- Enter Mitigation-Aware Scoring mode and update the relevant property attribute
- Update the attribute value and review any resulting score changes
- Submit the change and preserve the audit trail
Carriers Stay in Control
The carrier controls how Mitigation-Aware Scoring is used.
Carriers determine:
- Which users can submit or manage updates
- How long each update remains in effect
- What evidence or internal process is required before an update is applied
Original and updated values appear side by side with dates, making every change traceable. Updates apply only within that carrier's environment, so one carrier's updates do not change another carrier's scores.
Available Across ZestyAI Models
Mitigation-Aware Scoring is now available across all ZestyAI risk models, including Z-FIRETM, Z-HAILTM, Z-STORMTM, Z-WINDTM, Z-WATERTM, and Z-PROPERTYTM.
The Bigger Picture
Mitigation-Aware Scoring gives carriers a practical way to ensure underwriting and pricing decisions reflect verified property improvements.
It helps carriers:
- Recognize completed mitigation and maintenance
- Support policyholder requests to review property risk scores
- Support underwriting and pricing based on current property conditions
- Maintain an auditable record of each update
To see how ZestyAI risk models can support your underwriting and pricing workflows, book a demo.
Frequently Asked Questions About Mitigation-Aware Scoring
What is Mitigation-Aware Scoring?
Mitigation-Aware Scoring allows insurers to update verified property attributes within the ZestyAI platform and recalculate property risk scores when those changes affect the model.
Can property updates change a ZestyAI risk score?
Yes. Updates to model-relevant attributes can recalculate the risk score, and the platform records every change.
Which ZestyAI models support Mitigation-Aware Scoring?
Mitigation-Aware Scoring is available across Z-FIRE, Z-HAIL, Z-STORM, Z-WIND, Z-WATER, and Z-PROPERTY.
Ready to see how ZestyAI works on your book of business?
Tell us a little about your needs. We'll show you how we reduce losses and help you price with precision.