
Resources
Lilypad-Centauri Partners With ZestyAI to Strengthen Coastal Portfolio Using AI-Driven Risk Analytics
Lilypad-Centauri adopts roof and parcel-level insights to sharpen exposure data and strengthen risk decisions
ZestyAI today announced that Lilypad-Centauri is using ZestyAI’s Roof Age and Z-PROPERTY™ solutions to enhance its view of property risk across coastal homeowners and dwelling fire portfolios.
Lilypad-Centauri focuses on delivering stable and reliable coverage to homeowners and property owners in hurricane- and catastrophe-exposed coastal communities. By leveraging ZestyAI’s building attributes and parcel-level characteristics, Lilypad-Centauri gains a clearer view of property risk and how exposure accumulates across its coastal portfolio.
Lilypad-Centauri, through its managing general agency, is deploying two of ZestyAI’s proven solutions to gain a more granular, defensible view of property risk:
- Roof Age delivers verified roof age by cross-validating building permit records with over 20 years of aerial imagery, detecting roof replacement events, and assigning confidence scores across 97% of U.S. properties.
- Z-PROPERTY™ applies AI to high-resolution aerial imagery to assess roof complexity, materials, and condition, while evaluating parcel-level features such as vegetation overhang, yard debris, and secondary structures that influence claim frequency and severity across multiple perils.
“Coastal properties present a unique combination of exposure, from roof condition and construction features to how the parcel is maintained,” said Tony Hare, Chief Operating Officer & Chief Underwriting Officer of Lilypad-Centauri.
“ZestyAI’s roof and parcel-level analytics give us a clearer, property-level view of the homes we insure, helping us reduce uncertainty and better manage portfolio volatility.”
“Lilypad-Centauri is building a more resilient coastal portfolio by replacing exposure unknowns with verifiable property‑level truth,” said Attila Toth, Founder and CEO of ZestyAI.
“Granular, regulator-approved analytics bring confidence to the risk and capital decisions behind reliable customer protection.”
ZestyAI works closely with regulators to ensure transparency, validation, and continuous monitoring of its AI-driven models. Its portfolio of risk models has secured nearly 100 approvals from regulators nationwide, giving insurers confidence they can be deployed immediately with the accuracy and transparency regulators demand.
Where P&C Filings Go Off Track: The Execution Problem Behind Regulatory Delays
Regulatory delays in P&C filings are predictable, compounding, and largely fixable. A new ZestyAI research analysis of where filings actually break down shows the problem isn't primarily oversight — it's execution. Breakdowns cluster around a small number of recurring failure points, almost all of them early in the process, and once an objection cycle starts, delay compounds disproportionately with each round. The result is months of slippage that quietly erodes pricing effectiveness and consumes scarce actuarial and regulatory capacity.
About this analysis. Findings are drawn from analysis of recent P&C rate, rule, and form filings using ZORRO Discover, ZestyAI's AI agent purpose-built for insurance-specific research. The full report — Where P&C Filings Go Off Track — is an 8-page research analysis of filing breakdowns and the execution patterns that separate teams that manage delay from those that systematically reduce it.
Want the data? Download the full report →
Where do P&C filings actually go off track?
Not where most teams assume. Filings don't typically stall during deep technical review by regulators — they stall earlier, during submission, packaging, and initial support. Procedural gaps and missing exhibits trigger objections before reviewers ever engage with the substantive content of the filing. That's the first counterintuitive finding: a meaningful share of delay is generated before the regulator has even started evaluating the rate change, model factor, or rule update being filed.
The implication is that delay is largely an upstream problem with upstream fixes.
Why does delay compound once it starts?
Each objection round resets the review clock and expands the scope of scrutiny. What looks like a small clarification request adds weeks; a second cycle adds months; a third compounds further as the reviewer's questions broaden to adjacent assumptions. Once a filing is in the objection loop, timelines stretch disproportionately, not linearly. This is the second pattern: delay is non-linear, and most filing teams don't price the compounding cost of the second and third cycle into their internal timeline forecasts.
The carriers that move fastest are the ones that prevent the first objection — not the ones that respond to it well.
What does a late effective date actually cost?
The cost of delay is measurable, even when it's not always measured. Late effective dates scale impact in two directions at once: across the premium book affected by the change, and across the time the carrier operates under the prior (often inadequate) rates. A rate change that earns full approval three months late doesn't just lose three months of expected premium — it continues exposing the carrier to the loss patterns that motivated the change in the first place. Meanwhile, actuarial and regulatory teams burn cycles managing the objection process rather than building the next filing.
What do high-performing filing teams do differently?
They treat approval readiness as an operating capability, not a one-time deliverable. High-performing teams standardize how filings are packaged, build internal review against the procedural patterns regulators care about most, and use the institutional history of prior objections — their own and the market's — to anticipate the questions a reviewer will ask before the reviewer asks them. The performance gap between organizations isn't about regulatory environment or filing volume. It's about whether the filing function is built for speed.
What this means for 2026 product execution
As filings grow more complex and regulatory expectations rise, the gap is widening between organizations that manage delay and those that systematically reduce it. The pricing decisions, product changes, and risk responses being filed today only matter to the extent they reach the market when intended. Approval readiness is increasingly what separates carriers that translate strategy into results from those that watch their best work stall in the review queue.
Get the full report
Where P&C Filings Go Off Track →
The 8-page report walks through the specific breakdown patterns, where objection cycles start, how delay compounds across rounds, and how high-performing teams systematically reduce both.
Download the report — or request a trial of Zorro Discover to access the institutional filing history that lets teams anticipate regulator objections before they arrive.
ZestyAI Provides AI-Driven Risk Analytics for Marsh McLennan Agency
MMA’s Private Client Services division adopts wildfire, roof, and parcel-level insights to drive better outcomes for its high-net-worth clients
ZestyAI, the Risk and Decision Intelligence Platform for the insurance industry, today announced that Marsh McLennan Agency (MMA), a subsidiary of Marsh (NYSE: MRSH), has adopted its risk analytics
By leveraging three cutting-edge solutions from ZestyAI, Z-FIRE™, Roof Age, and Z-PROPERTY™, the MMA Private Client Services team was able to improve wildfire risk evaluation for these homeowners by analyzing detailed property data and loss history and assessing roof age and condition using high-resolution aerial imagery. This strategic deployment enhanced their ability to offer more precise, customized insurance and risk management solutions for their clients’ high-value homes.
“Safeguarding the lifestyles and legacies of our clients requires a forward-looking approach to risk,” said Robert Pritula, Senior Vice President, National Placement and Solutions Leader of MMA’s Private Client Services division.
“We are always looking for new ways to leverage cutting-edge technologies that will allow us to offer clients tailored and effective solutions to mitigate the threats facing their most valuable assets, including their homes.”
“MMA has built its reputation on exceptional client service and proactive risk management,” said Attila Toth, Founder and CEO of ZestyAI.
“With granular risk analytics backed by industry standards and proven accuracy, they are leading the way in how high-value portfolios can be protected with confidence.”
ZestyAI works closely with regulators to ensure transparency, validation, and continuous monitoring of its AI-driven models. Its portfolio of models has secured more than 80 approvals from regulators nationwide, including Z-FIRE™, which has been approved across every wildfire-prone state, giving insurers confidence they can be deployed immediately with the accuracy and transparency regulators demand.
What Winter Storm Fern Reveals about Interior Water Losses and Systemic Risk
ZestyAI Product Insights
Winter Storm Fern has evolved into a historic catastrophe for the U.S. insurance industry. Between January 23-27, 2026, the storm shattered records by placing over 230 million Americans under severe winter alerts, with a death toll of 85 as of February 3rd.
Preliminary industry estimates place insured losses at $6.7 billion, potentially making Fern the third-costliest U.S. winter storm on record, trailing Elliott (2022) and Uri (2021). The crisis is far from over. The National Weather Service warns of a "historic duration" of extreme cold, with temperatures 15 to 25 degrees below average, that continues to hamper mitigation efforts.
For carriers, Fern is a complex, multi-peril challenge. Claims teams are navigating a surge of freeze-related losses, ice-driven structural damage, and widespread business interruptions across 34 states.
To understand the stakes, one needs to look no further than February 2021, when Winter Storm Uri brought Texas to its knees and generated over $11 billion in insured losses from a single state. Fern’s footprint is broader, and its secondary effects are still unfolding.
The Cold Hard Numbers from Storm Uri: Why Claims Explode Below 5°F
Our analysis of the 2021 Storm Uri reveals a striking relationship between temperature deviation and claim frequency for the non-weather water and freeze perils. Using data from multiple carriers, we tracked daily claim rates against minimum temperatures: before, during, and after the storm window (February 11-20, 2021).
The results show how rapidly falling temperatures can transform a routine winter pattern into a systemic loss event, allowing us to monitor the market’s response in real-time as conditions deteriorated, peaked, and normalized.
The results are dramatic:
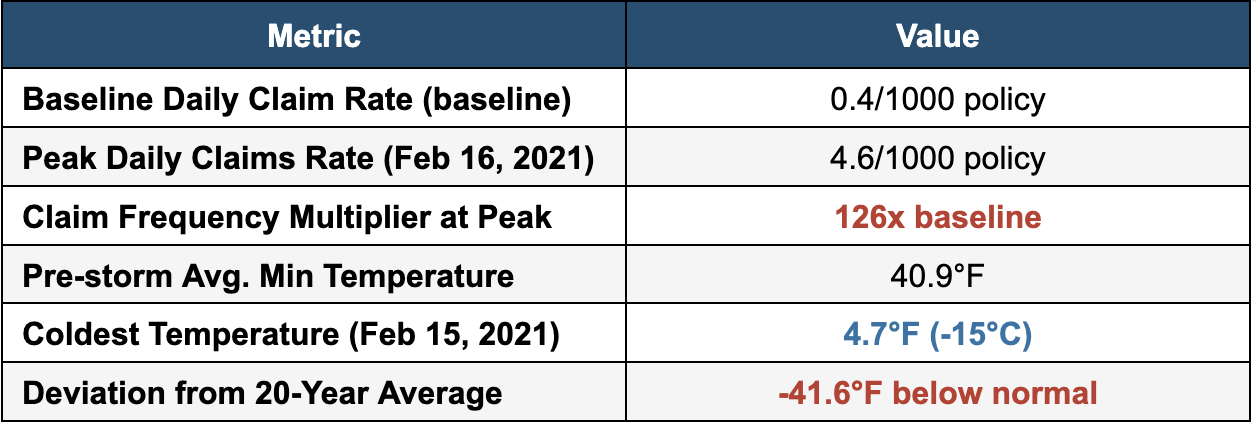
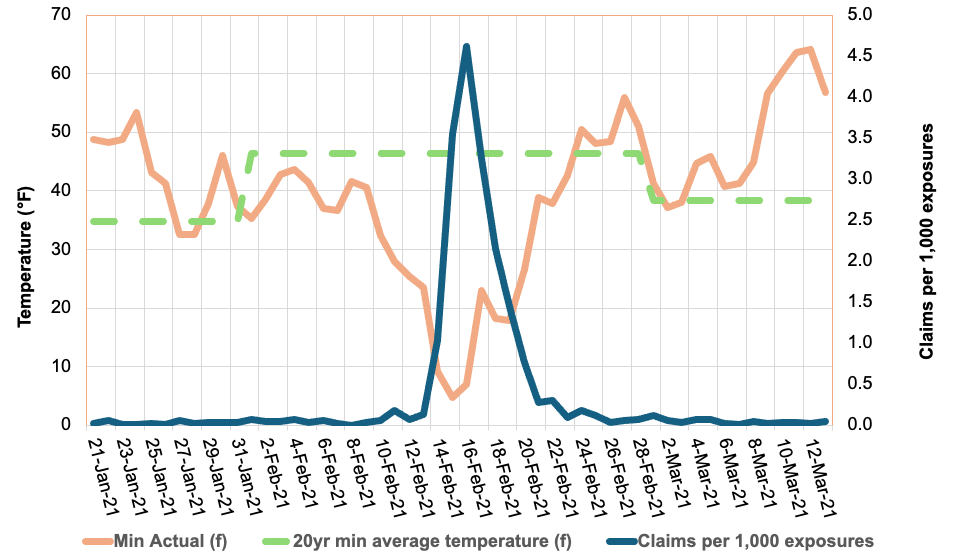
Figure 1: Daily claim rates (blue line) surged 126X above the baseline in a temporal spike as temperatures (orange line) plunged below the 20-year average (dashed green line) during Winter Storm Uri.
The chart reveals a clear inverse relationship: as minimum temperatures dropped from the mid-40s°F to below 5°F, daily claim rates didn’t just rise, they increased 126X, from a baseline of 0.04% to 0.46% at the peak. This dramatic surge underscores the significant consequences of extreme cold events on insurance liability.
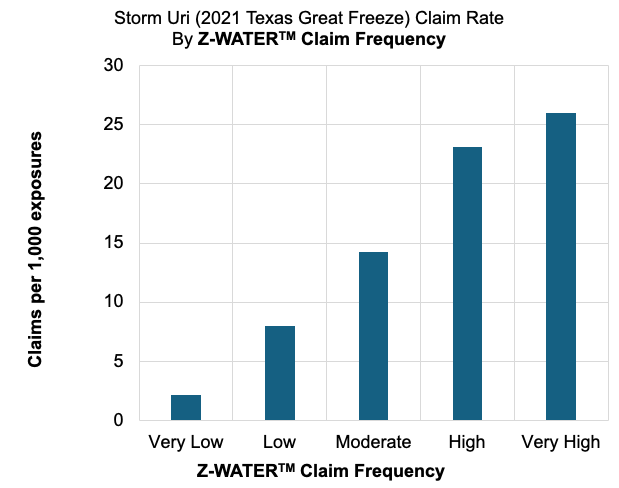
Figure 2: ZestyAI’s Z-WATER™ demonstrated an 11X increase in claim frequency between ‘Very High’ and ‘Very Low’ risk tiers during Winter Storm Uri
We used ZestyAI’s Z-WATER™ to segment the property-specific non-weather water risk across the 10-day storm window. Z-WATER™ is a risk model that accounts for how plumbing design, local climate, and infrastructure reliability interact to drive non-weather water and freeze losses. By capturing real-world dynamics, such as temperature swings that stress pipes and electrical grid failures that amplify claims, the model delivers a scientifically grounded view of property-level risk.
The results were definitive: properties that Z-WATER™ scored as ‘Very High’ risk filed 26 claims per 1,000, compared to just 2.2 claims per 1,000 for those scored as ‘Very Low’, an 11X increase in claim frequency.
This accurate segmentation reveals a clear path to managing volatility. Z-WATER™ provides a deep understanding of a home’s resilience across the full spectrum of loss mechanisms, from everyday plumbing failures to expensive outlier events like Storms Uri and Fern. By enabling precise intra-territory risk splitting, the model allows carriers to price and underwrite more reliably, ensuring premiums reflect the true risk profile while protecting the portfolio against systemic losses.
The January 2026 Storm: History Rhyming?
While we can already see the immediate impact of Winter Storm Fern, the primary difference between Fern and Winter Storm Uri is the duration of the freezing event itself, rather than any changes in how quickly policyholders are filing their claims.
As shown in Figure 1, NWW claims rise rapidly as temperatures fall and taper off quickly once conditions normalize. The risk in prolonged cold events lies in how long properties stay below the Plumbing Design Temperature; the longer the freeze, the greater the likelihood of systemic plumbing failure.
During Winter Storm Uri, extended sub-freezing conditions significantly increased the number of days in which vulnerable properties were exposed to frozen pipe failures, driving aggregate losses to historic levels. Fern is now exhibiting a similar duration profile, with sub-freezing conditions persisting for up to 10 consecutive days across parts of the Northeast. The National Weather Service has warned this “could be the longest duration of cold in several decades,” raising the likelihood of elevated losses even if individual claims remain tightly clustered in time.
For carriers, the warning signs are already flashing:
- The Power Failure Multiplier: During the storm's peak, over 1 million customers lost power. In the South, where homes lack the heavy thermal insulation of northern properties, a power outage is the primary driver of catastrophic pipe bursts. Without active heating, a property can reach the "burst threshold" within hours.
- The $30,000 Claim Severity Benchmark: Recent State Farm data underscores the high stakes of these events. Winter water damage claims totaled over $628 million, with the average claim payment now exceeding $30,000. For carriers, this high per-claim severity means even a moderate frequency surge can quickly erode Q1 margins.
- Regional Fragility in the South: While the initial assessments are still surfacing, early industry estimates for privately insured losses from Winter Storm Fern puts the damage at $4 billion to $7 billion. With Texas and Tennessee identified as the hardest-hit states, carriers are facing a "Uri-style" scenario in which infrastructure wasn't designed for a 10-day deep freeze.
From Reactive to Predictive: Solving the $6.7 Billion Freeze Risk Equation
The 2021 Texas freeze taught us that traditional approaches to freeze risk are highly insufficient. Many properties that experienced burst pipes were in areas that rarely see extended freezing temperatures, meaning they lacked adequate winterization.
This is where predictive analytics becomes essential. By modelling the interaction between property-level vulnerabilities and local temperature thresholds, carriers can better identify which properties are most vulnerable to freeze events before the damage actually occurs.
Key Risk Drivers Identified in Our Latest Analysis:
- The Design Mismatch: The greatest risk isn't just the cold; it's the sudden change in temperature. Properties in states like Texas or Tennessee face a higher risk because they are built to release heat, not trap it. They lack the heavy insulation and deep-buried pipes needed to survive a 10-day freeze.
- The Power Grid Vulnerability: Our analysis shows that areas prone to power outages face a compounded risk. In the South, a home’s primary defense is its heating system so when the power fails and the heater stops, the "burst threshold" can be reached in just a few hours.
- Building Vulnerabilities: Our analysis shows that older homes and properties with plumbing routed through exterior walls are disproportionately represented among $30,000 non-weather water losses.
The Bottom Line for Carriers
The 2021 Texas freeze was a pivotal moment for the industry, generating more than 500,000 claims and $11.2 billion in insured losses in a single state. Today, Winter Storm Fern represents an even broader systemic threat, with weather alerts impacting 230 million people across more than 30 states.
While the final tally for Fern is still developing, the data is already clear: temperature shocks drive claims at exponential rates. With early industry assessments estimating privately insured losses between $4 billion and $7 billion, it is evident that the prolonged duration and geographic anomaly of extreme weather events are the primary drivers of this volatility.
For carriers looking to protect their Q1 margins, predictive analytics are no longer a luxury; they are a requirement. By analyzing property-level characteristics, regional vulnerabilities, and historical temperature deviations, you can move from reactive claims handling to proactive risk management.
The question isn't whether another major freeze will occur, but whether your portfolio is prepared for the next 126-fold surge.
Learn More About Z-WATER
ZestyAI’s Z-WATER™ provides the industry’s most granular view of interior water risk, helping carriers accurately and reliably assess properties in areas prone to temperature shock events. By analyzing detailed property-level characteristics alongside historical weather patterns and regional risk factors, our advanced models predict the likelihood of Non-Weather Water (NWW) and freeze claims as well as their associated severity. This deeper level of analysis empowers carriers to make smarter pricing decisions before the next major storm hits.
Methodology: Analysis based on aggregated claims from multiple Texas carriers during Winter Storm Uri (February 2021). Temperature data reflects mean daily minimums across the exposure footprint, weighted by ZIP Code to account for geographic density. The claim/exposure ratio was calculated by dividing daily claims by the average policy-day exposure.
-----------------------------------------------------------------
1CNN Weather, "More than 230 million people under alerts for potential ice, heavy snow and extreme cold," January 2026. [link]
2Fox News, "Noem coordinates with Mississippi officials as state recovers from deadly winter storm," January 2026. [link]
3Insurance Innovation Reporter, “KCC Estimates $6.7 Billion in Insured Losses from Winter Storm Fern,“ February 2026 [link]
4Texas Department of Insurance, "Insured Losses Resulting from the February 2021 Texas Winter Weather Event," March 2022. [link]
5Fox Business, “More than 1 million Americans lose power as monster winter storm sweeps across the US,” January 2025 [link]
6Carrier Management, “Frozen Pipes Lead to $628M in Losses for State Farm,” January, 2026 [link]
7 Barrons, “Winter Storm Fern Packed a Wallop. Now the Cost Estimates Are Rolling In.,“ February 2026 [link]
Logic Underwriters Adopts ZestyAI to Strengthen Texas Property Underwriting with AI-Powered Hail and Wind Models
Storm and property insights help inform risk-aligned coverage decisions
ZestyAI today announced that Logic Underwriters has adopted ZestyAI’s Z-PROPERTY™, Z-HAIL™, and Z-WIND™ solutions to improve underwriting and rating precision across its personal and commercial property portfolio in Texas.
Texas is the most expensive severe convective storm market in the United States, with hail and damaging wind driving billions of dollars in insured losses every year.
"Texas is one of the most challenging storm markets in the U.S., and we need tools that match that reality," said Bill Motz, Director of Operations, Logic Underwriters.
"ZestyAI's detailed property insights and dedicated hail and wind models will help us continue to provide exemplary service to our clients—from more accurate risk assessments to better loss prevention guidance in increasingly volatile weather conditions."
ZestyAI’s property-specific hail and wind models predict the likelihood and severity of storm-driven claims by analyzing how local climatology interacts with detailed property characteristics—helping underwriters to distinguish meaningful differences in risk within the same rating territory. Each model is trained on validated claims data, offering transparent explanations of the key factors driving risk.
Z-PROPERTY applies AI to high-resolution aerial imagery and multi-source data to assess roof condition, structural complexity, and parcel-level features such as vegetation overhang, yard debris, and secondary structures—factors that directly influence claim frequency and severity across multiple perils.
“Logic Underwriters is exactly the kind of forward-looking partner that is redefining underwriting in high-exposure states,” said Attila Toth, Founder and CEO of ZestyAI.
"This collaboration shows how property-level intelligence can support underwriting excellence and disciplined decision-making while helping policyholders better understand and protect their properties. When insurers can identify specific risk factors like roof condition or vegetation overhang, they can provide actionable guidance that helps clients reduce their exposure and minimize losses."
ZestyAI’s severe convective storm models are approved in 30 states, spanning the nation’s highest-exposure hail and wind markets, and used by leading insurers across the country.
Nearly $1 Trillion in California Homes Labeled “Low Risk” Despite Elevated Wildfire Danger
Wildfire risk in the United States is no longer confined to the edges of forests or traditionally high-risk zones. New analysis using ZestyAI’s property-level wildfire models shows that millions of homes classified as low or no wildfire risk under federal assessments face elevated wildfire danger when evaluated at the property level.
This analysis was recently featured in Vox, which examined how wildfire behavior is evolving — and why broad, backward-looking risk maps are increasingly misaligned with how fires spread today.
👉 Read the full article on Vox → https://www.vox.com/climate/476932/california-wildfire-los-angeles-risk-ai-housing-climate
Wildfire risk is closer — and more granular — than most maps show
Many homes damaged or destroyed in the 2025 Los Angeles wildfires were still classified as “low risk” under federal wildfire assessments. ZestyAI’s property-level analysis provides a different perspective.
By evaluating individual structures — including vegetation proximity, defensible space, building characteristics, and neighborhood-level fire dynamics — ZestyAI identified more than 3,000 properties worth approximately $2.4 billion in areas impacted by the Palisades and Eaton fires that showed elevated wildfire risk despite being classified as low or no risk under FEMA’s census-level assessments.
Across California, the classification gap is even broader. Approximately 1.2 million properties, representing roughly $940 billion in residential property value, are designated as low or no wildfire risk under federal maps, despite AI-driven property-level models indicating elevated wildfire danger.
Why census-level wildfire maps fall short
Wildfires do not spread evenly across census tracts or counties. Ember-driven ignition, structure-to-structure spread, wind conditions, and localized vegetation patterns create uneven outcomes, where one home survives and the next is destroyed.
Federal wildfire assessments are designed to provide a baseline view of community-level risk. FEMA has noted that its National Risk Index is not intended to serve as a property-specific risk assessment. When risk is evaluated at the individual property level, meaningful differences emerge that aggregated maps are not designed to capture.
What more granular wildfire risk intelligence enables
More detailed wildfire risk data can support:
- Targeted mitigation efforts at the property and neighborhood level
- More informed rebuilding and land-use decisions
- Clearer, more defensible underwriting and portfolio strategies
- Improved dialogue between insurers, regulators, and communities
A shift in how wildfire risk is understood
Wildfire risk is evolving faster than the systems built to measure it. Homes are no longer just adjacent to wildfire hazards; they increasingly influence how fires ignite, spread, and intensify, even in dense urban environments.
Property-level risk intelligence does not remove hard decisions. But without it, those decisions are made using an incomplete picture of where wildfire risk truly exists.
Read the full Vox article here.
Ready to see how ZestyAI works on your book of business?
Tell us a little about your needs. We'll show you how we reduce losses and help you price with precision.